Renovation Loans in Singapore: Cap and Costs
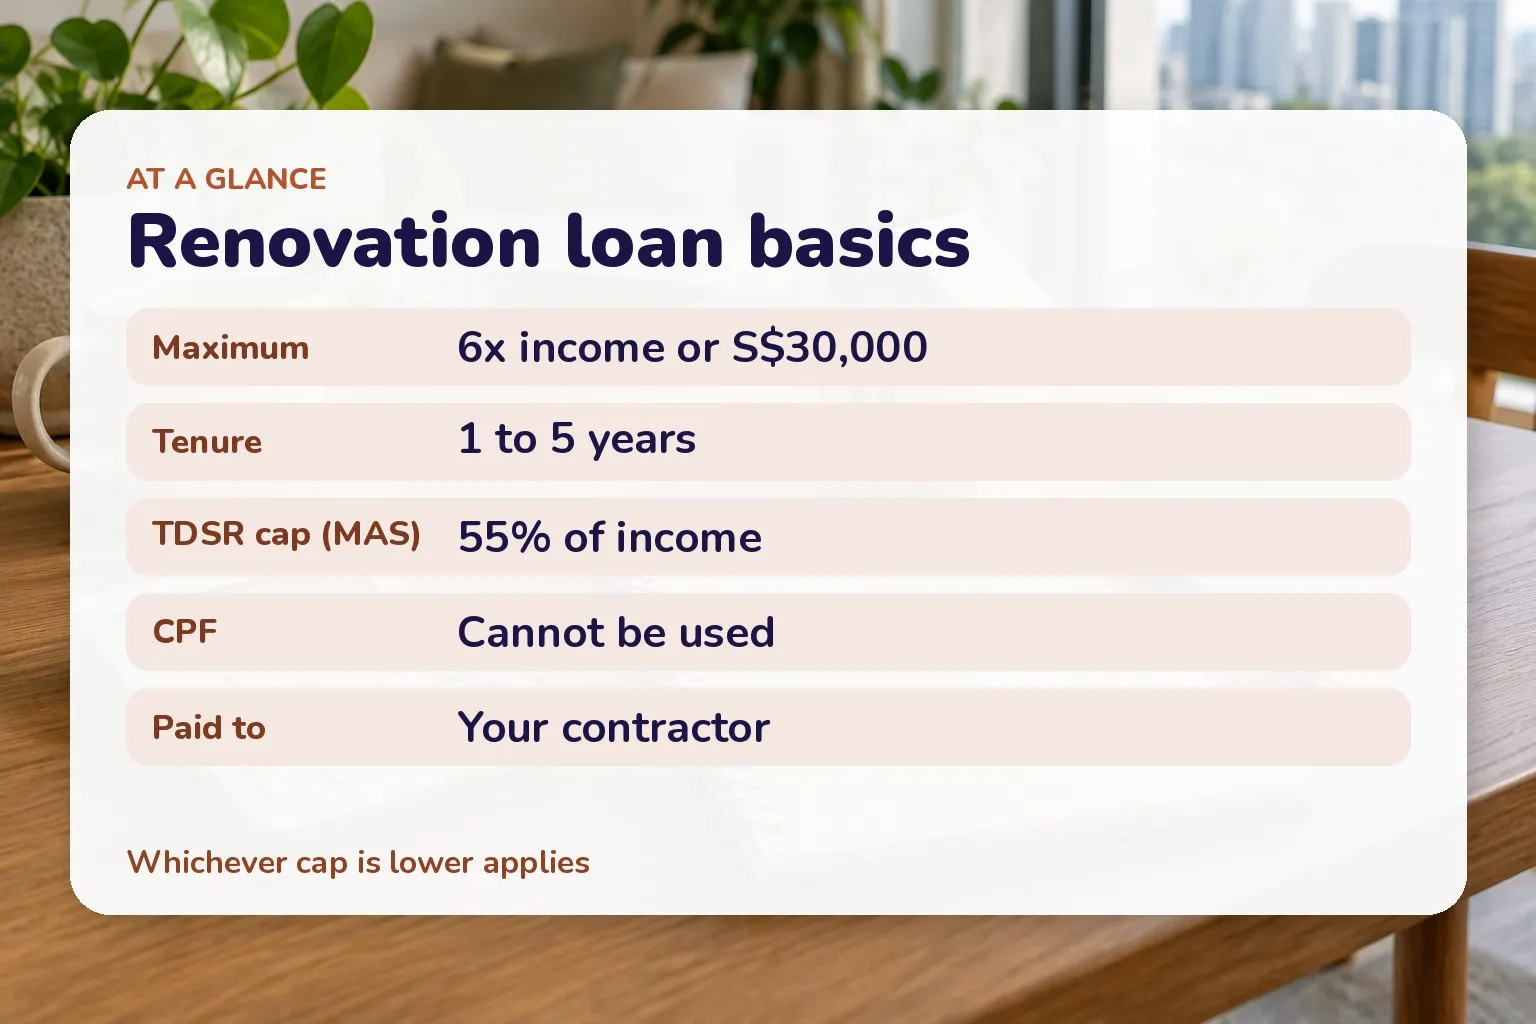
A Singapore renovation loan is capped at the lower of 6× your monthly income or S$30,000, repaid over one to five years. CPF cannot repay it, and the bank disburses the money straight to your contractor.
On this page (4 sections)
A renovation loan can smooth the cash flow of a renovation, but it is deliberately small. Knowing its limits up front stops it from shaping your whole budget by accident.
The two hard caps
Across Singapore banks, a renovation loan is capped at the lower of six times your monthly income or S$30,000. So someone earning S$4,000 a month qualifies for about S$24,000 (6 × S$4,000), while anyone earning S$5,000 or more is held at the S$30,000 ceiling — earning more does not unlock a bigger loan. Joint applications are usually assessed on combined income, which is how many couples reach the cap.
The core limits of a Singapore renovation loan. Source: MAS; SingSaver, 2026.
On top of that, the Monetary Authority of Singapore’s Total Debt Servicing Ratio (TDSR) framework applies: your total monthly debt repayments, including the new loan, must not exceed 55% of your gross monthly income. A large car loan or a new mortgage can therefore reduce what you are approved for, even if the 6× / S$30,000 maths says otherwise.
Tenure, CPF and how it’s paid
- Tenure runs from 1 to 5 years. A longer tenure lowers the monthly payment but raises the total interest you pay.
- CPF cannot be used to repay a renovation loan — it must come from cash or salary.
- The loan is normally disbursed directly to your contractor, not into your account, so it can only pay for renovation works.
An illustrative instalment
Interest is the part that varies by bank and promotion, so treat this as illustrative arithmetic, not a quoted rate. If you borrowed the full S$30,000 over 5 years at a hypothetical flat rate of 4.5% per year:
- Interest ≈ S$30,000 × 4.5% × 5 = S$6,750
- Total repayable ≈ S$36,750
- Monthly ≈ S$36,750 ÷ 60 = about S$613
A shorter tenure raises the monthly figure but cuts total interest. Advertised “flat” rates also look lower than the effective interest rate (EIR), so always compare EIR when you shop. You can try different amounts, tenures and rates in the renovation loan calculator. Confirm the actual current rates with the bank.
When a renovation loan isn’t enough
Most full renovations cost more than S$30,000 — see the HDB renovation cost guide and the 4-room BTO breakdown. The shortfall has to come from cash or another facility (such as a personal loan for furniture and overruns). Plan the loan as one piece of the budget, alongside a 10–20% buffer, in the first-time renovation guide.
Related
- HDB renovation cost guide
- 4-Room BTO renovation cost breakdown
- First-time renovation: the full guide
General information for comparison only, not financial advice or a product recommendation. Rates and rules change; confirm current terms with the bank and MAS.
Sources
- Total Debt Servicing Ratio (TDSR) framework — Monetary Authority of Singapore (MAS) (as of October 2026)
- How Much Renovation Loan Can I Get in Singapore? — SingSaver (as of October 2026)